Home Blog Page 289

People Who Don’t Know How to Code Make 6 Figures By Cashing In On the $4.7 Billion ‘Vibe Coding’ Boom

0
People Who Don’t Know How to Code Make 6 Figures By Cashing In On the $4.7 Billion ‘Vibe Coding’ Boom


Opinions expressed by Entrepreneur contributors are their own.

The four moves any non-coder can use to launch a one-person business this week.

Key Takeaways:

  • Discover what “vibe coding” really means — and why 63% of the people using it to build real businesses have never written a line of code.
  • Watch how one solo founder built a $401 million business in year one with $20K and his brother as his only employee.
  • Screenshot the exact Perplexity Computer prompts that reverse-engineer what four solo founders did to build their businesses — without figuring it out from scratch.

You have the idea. You have the laptop. You have every AI tool on the market open in a tab. And you are still not launching anything.
That is the quiet frustration behind the biggest shift in one-person business formation of the last decade. The tools are here. Most solopreneurs are still waiting to feel technical enough to start. The founders in the video above stopped waiting — and the moves they made are not what most solopreneurs expect.

The four moves I break down in the video above are designed to fix that — starting with the one most non-coders skip.

“Vibe coding” is the term Andrej Karpathy, one of the co-founders of OpenAI, coined in early 2025 to describe a new way of building software. You describe what you want in plain English, an AI writes the code, and you refine it by conversation instead of syntax. It sounded like a joke a year ago. According to Startup Fortune, it is now a $4.7 billion market growing at 38% a year, with 63% of active users identifying as non-developers.

This is not a fringe movement. Axios reported in June that Americans are starting one-person businesses 20% faster than they were a year ago, while startups planning to hire employees have stayed flat — a shift Nasdaq’s economists tie to autonomous coding tools. Intuit’s 2026 AI Impact Report, built on more than 34,000 SMB owners, found that 43% of AI-using businesses say AI has increased their revenue, versus just 2% who say it has gone the other way.

That compression is what Rule 5 of my book, The Wolf Is at the Door, is really about. In a world where the software builds itself, adaptability is no longer about learning faster than the market — it is about shortening the loop between what you see and what you launch. The reason a solo founder can now sell a company for $401 million with almost no employees is not that AI made him smart. It is that AI has collapsed the reaction time that used to give bigger competitors the advantage. That opportunity is now in your hands, no seven-figure marketing budget required.

This weeks video breaks down how Matthew Gallagher launched Medvi in two months with $20K and his brother as his only employee, how Billy Howell charges $750 to $2,500 per app with no coding background, how the creator behind BridgeMind made $42,630 in 142 days building live on YouTube, and how KEV hit $100,000+ in revenue and 67,000 users across four apps — plus the four Perplexity Computer prompts to reverse-engineer their moves in your own business this week.

Every founder, every move and every prompt is walked through in the video above — including the four Perplexity Computer prompts that turn what took these founders months of trial and error into a single afternoon of work.

The free AI Success Kit, available to download for a limited time, comes with a free chapter from my new book, The Wolf is at The Door – How to Survive and Thrive in an AI-Driven World.

The four moves any non-coder can use to launch a one-person business this week.

Key Takeaways:

  • Discover what “vibe coding” really means — and why 63% of the people using it to build real businesses have never written a line of code.
  • Watch how one solo founder built a $401 million business in year one with $20K and his brother as his only employee.
  • Screenshot the exact Perplexity Computer prompts that reverse-engineer what four solo founders did to build their businesses — without figuring it out from scratch.

You have the idea. You have the laptop. You have every AI tool on the market open in a tab. And you are still not launching anything.


Source link

XRP price jumps 2% on bitcoin strength as buyers push through $1.10 resistance

0
XRP price jumps 2% on bitcoin strength as buyers push through $1.10 resistance

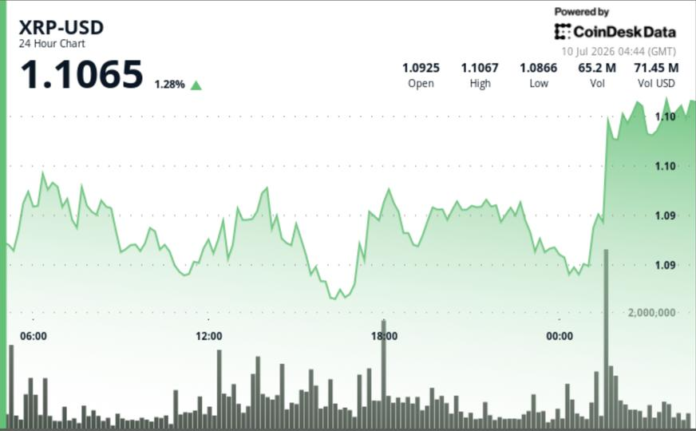
• The main breakout came around 01:00 UTC, when volume jumped to 43.51 million XRP, about 88% above the 24-hour average.

• The move carried XRP to an intraday high of $1.1065 before price stabilized near $1.1020-$1.1040.

• A later 60-minute spike reached 14.17 million in volume, pushing XRP from $1.0958 to $1.1052 before profit-taking slowed the move.

Technical Analysis

• The key development is that XRP cleared the $1.0950-$1.1000 area after several sessions of range-bound trading.

• The breakout was supported by volume, which gives the move more weight than the earlier low-volume attempts above resistance.

• Higher lows through the session show buyers are stepping in earlier, with $1.0880 acting as the main support level during pullbacks.

• The post-breakout hold near $1.1020-$1.1040 is constructive because XRP did not immediately lose the $1.10 area after the spike.

• The next test is whether buyers can keep XRP above $1.10 long enough to challenge $1.1065 and then $1.13.

What traders should watch

• $1.10 is the immediate support level after the breakout.

• $1.0880 is the next level to watch if XRP slips back into its prior range.

• $1.1065 is the first resistance after marking the session high.

• $1.11 is the next psychological level, followed by $1.13 if momentum continues.


Source link

Gold prices today, Friday, July 10, 2026: Gold finally opens higher this morning

0
Gold prices today, Friday, July 10, 2026: Gold finally opens higher this morning


Gold (GC=F) August futures opened at $4,135.40 per troy ounce on Friday, July 10, 2026, up 1.2% from Thursday’s opening price. The gold price moved slightly lower this morning to $4,115.10 at 8:00 a.m. ET.

Gold prices opened higher this morning, reversing a trend of opening lower each day so far this week. Today’s opening price for gold is 1.2% higher than Thursday’s opening price, but still 1.2% lower than where prices began this week.

Gold spent much of the week falling because the U.S. and Iran reengaged in military conflict this week, sending oil prices higher and putting a permanent peace deal with Iran in real jeopardy. Oil prices (BZ=F) are currently up 7.1% over the last five days, putting rising inflation back at the forefront of Fed discussions.

Despite these renewed inflation worries, there is just a 25.1% chance the Fed will raise rates following their two-day meeting at the end of July. That percentage jumps to nearly 50% following their September meeting, according to the latest percentages in the CME Group’s FedWatch tool.

The opening price of August gold futures on Friday was 1.2% higher compared to Thursday’s opening price. Here’s a look at how the gold price has changed versus last week, month, and year:  

  • One week ago: +1.7%

  • One month ago: -1.5%

  • One year ago: +24.4%

On Jan. 29, gold’s one-year gain was 95.6%.

24/7 gold price tracking: Don’t forget you can monitor the current price of gold on Yahoo Finance 24 hours a day, seven days a week. 

Want to learn more about the current top-performing companies in the gold industry? Explore a list of the top-performing companies in the gold industry using the Yahoo Finance Screener. You can create your own screeners with over 150 different screening criteria.

A gold investment can add stability and inflation protection to your portfolio. But it can also dilute your gains when stock prices are rising quickly. Finding the right balance between gold’s diversification benefits and profiting from growth potential in other assets can be challenging. 

Even the experts are divided on how to achieve the correct balance. Below, five experts explain their recommended gold allocations, which range from 0% to 20%. 

Learn more: How to invest in gold in 4 steps

Robert R. Johnson, professor at Creighton University’s Heider College of Business, does not advocate gold investing. In his words, “while having a small position in precious metals may dampen portfolio volatility in the short-run, the tradeoff between slightly dampened volatility and the lost long-term return is certainly not a prudent one, particularly for Gen Z/millennials with long investing time horizons.”

Brett Elliott, director of content and SEO at American Precious Metals Exchange (APMEX), recommends setting an allocation that aligns with your investing goals. 

Growth-oriented investors may be comfortable with an allocation of 10% or 15%, according to Elliott. But income investors will prefer a smaller position, because gold provides no yield. A 2% to 5% gold allocation can provide some resiliency without an excessive drag on income potential. 

Learn more: Who decides what gold is worth? How gold prices are determined.

Blake McLaughlin, executive vice president at Axcap Ventures, said historical data support a gold allocation of 5% to 8%. “Gold may not offer the outsized return potential of private investments, but the metal holds a set of attributes that are increasingly hard to ignore,” according to McLaughlin. Those attributes include the metal’s resilience amid economic uncertainty and geopolitical unrest. 

Thomas Winmill, portfolio manager at Midas Funds, believes most investors will benefit from a long-term gold allocation of 5% to 15%. Winmill specifically advocates investing in gold mining companies through a mutual fund. 

Your risk tolerance and current mix of financial versus hard assets can guide you to an appropriate allocation, according to Winmill. 

  1. Risk tolerance: Keep your allocation percentage low if you tend to panic in volatile cycles.  

  2. Financial vs. hard assets: Financial assets are stocks and bonds. Hard assets include tangible items like real estate, gold, collectibles, classic cars, and equipment. If you have no home equity and your wealth is primarily in financial assets, you can set your gold allocation higher. Or, if your home is paid for and more valuable than your stock portfolio, gold investing may not be necessary.  

Learn more: Thinking of buying gold? Here’s what investors should watch for.

Vince Stanzione, CEO and founder at First Information, recommends a 20% gold allocation, specifically in physical gold or a gold ETF. Stanzione argues for a higher exposure to gold as a wealth protection strategy. As he says, “gold keeps with inflation and gold retains its purchasing power,” while paper currencies are devaluing around the world.   

Learn more: Gold IRA: Benefits, risks, and how it differs from a traditional IRA

Whether you’re tracking the price of gold since last month or last year, the price-of-gold chart below shows the precious metal’s change in value so far this year. 


Source link

Metaplanet announces join study to bring BTC-powered digital credit to Japan

0
Metaplanet announces join study to bring BTC-powered digital credit to Japan

“The four companies will examine issues in product design, the need for proof-of-concept initiatives, and the possibility of future issuance,” Metaplanet said in a statement. “At this time, nothing has been determined regarding issuance timing, terms, yield, product details, distribution methods, or the form of collaboration.”

Japan’s traditional credit market leans in favor of large corporations with public bond offerings. Mid-sized and growth companies often face high costs and operational burdens around issuance, sales, investor management, interest payments and redemptions, according to Metaplanet.

Digital credit could open the debt market to these smaller companies, bridging traditional capital markets with onchain technology, enabling 24/7 global trading and settlement, holder-level rights management, automated pro-rata interest calculations and transparent onchain payments/redemptions.

Key roles

Each company is bringing its own strength to the table. Metaplanet and its securities arm will design and create the new products that combine bitcoin with credit offerings. They’ll also handle selling them to investors, communicating with customers, and managing everything afterward.

JPYC will explore the use of its stablecoin in the process, making sure it can be used smoothly for payments and redemptions.

Progmat will provide a secure, regulated system for turning the products into digital tokens on the blockchain. This includes tracking ownership, handling transfers, and connecting everything to the stablecoin payments system.


Source link

Seller-paid rate buydown: How it works and how to ask for one

0
Seller-paid rate buydown: How it works and how to ask for one


A seller-paid rate buydown may be the mortgage-rate relief that hopeful homebuyers are looking for. Few house hunters might imagine the seller coming to their rescue, but it’s possible, and in some real estate markets, even likely. Here’s how.

When marketing a home-for-sale listing, sellers often need to generate more interest. That’s where open houses, advertising, and price reductions come into play. There are also seller concessions. Those are cash or closing-cost credits issued by the seller and used as incentives for potential buyers.

A rate buydown is a powerful marketing tool where the seller pays to lower the buyer’s mortgage rate.

➡ Read more: Seller concessions vs. credits

Rate buydowns can be either permanent or temporary.

A permanent seller-paid rate buydown is when the seller buys discount points to lower a buyer’s mortgage rate for the life of the loan. 

“If the seller is a builder, developer, or has other properties in the area, they may choose to offer a rate buydown versus a price cut, in order to maintain values and comps for their other properties,” Lindsey Harn, of the Lindsey Harn Group in San Luis Obispo, California, told Yahoo Finance. “Sometimes sellers also want to keep the comps high for their neighbors, or simply be stuck on hitting a certain sales price for their home.”

A temporary seller-paid rate buydown lowers the buyer’s mortgage rate only for a specified time. The seller makes a cash contribution to the mortgage escrow account to fund the temporary rate cut. For example, a 2-1 buydown lowers the rate by 2% in the first year and 1% in the second. For the third year and the remaining term of the loan, the borrower will pay the issued mortgage rate. 

“As a buyer, a temporary rate buydown can be great if you expect your income to increase over the next two to three years,” Harn said. “However, as a buyer, if you think rates are going to drop and you are going to want to refinance in the next two to three years, the funds spent on the rate buydown can be a ‘waste’ of money.”

Read more: Temporary vs. permanent rate buydown

Negotiating the purchase of a home will fall to your buyer’s agent. However, if you’re interested in exploring a seller-paid rate buydown, it’s worth asking your agent if the local real estate market is prone to such seller concessions. It’s also not a bad idea to get a second opinion or two.

If you’re seeing other listings similar to the one you’re pursuing that promote buydowns, press the matter with your agent, politely, of course. Some agents are better than others at negotiating a deal. 

If you’re a hands-on negotiator, make sure you:

  • Have a mortgage preapproval in hand. 

  • Have researched your local real estate market. A buyer’s market is more conducive to seller concessions, such as rate buydowns. 

  • Know the cost of the buydown you’re proposing by talking to your lender.

  • Have your real estate agent put the specific buydown details in your purchase agreement or counteroffer.

  • A lower interest rate can enhance the affordability of a home purchase.

  • A seller-paid rate buydown may be more valuable to a buyer than a price cut on the house. Use a mortgage payment calculator to run various scenarios. 

  • Even a temporary buydown can help new buyers transition to homeownership by providing a budget cushion for moving expenses, furniture, or home improvements.

  • A temporary buydown might put you in a budget squeeze when the higher interest rate kicks in to your monthly payment.

  • A permanent buydown lowers only your interest rate. A price cut of an equal amount may also lower your property taxes.

  • Depending on the type of loan, there are limits to seller concessions, most commonly ranging from 3% to 6%, though up to 9% on conventional loans with more than 25% down.

One discount point generally reduces a mortgage rate by about 0.25%, so for a life-of-the-loan 1% reduction in the interest rate, four discount points would be required. That would equal 4% of a home’s purchase price. For example, on a $400,000 home, four discount points would cost $16,000.

A 2% buydown can be either a permanent or a temporary interest rate reduction. A seller may offer to lower the buyer’s mortgage rate by 2% for the first year, such as in a 2-1 buydown, or for the life of the loan. 

A seller can generate more buyer leads by offering a temporary rate buydown. This is particularly useful in a buyer’s market, where there are more homes for sale than there is demand. 

➡ Read more: Understanding housing inventory

Under the right circumstances, both the buyer and seller can benefit. A buyer can get a lower mortgage rate, and the seller can drive more interest to their listing — and perhaps do it at a lower cost than reducing the asking price. 


Source link

‘The stacking continues,’ says unfazed Eric Trump despite $600M Bitcoin venture wipeout

0
'The stacking continues,' says unfazed Eric Trump despite $600M Bitcoin venture wipeout


Eric Trump’s stake in Bitcoin mining and treasury firm American Bitcoin Corp. has been devalued by about $600 million, according to a Bloomberg report. 

He owns about 6% of the firm and doubles as American Bitcoin’s Chief Strategy Officer. His brother, Donald Trump Jr., also owns an undisclosed stake in the firm.

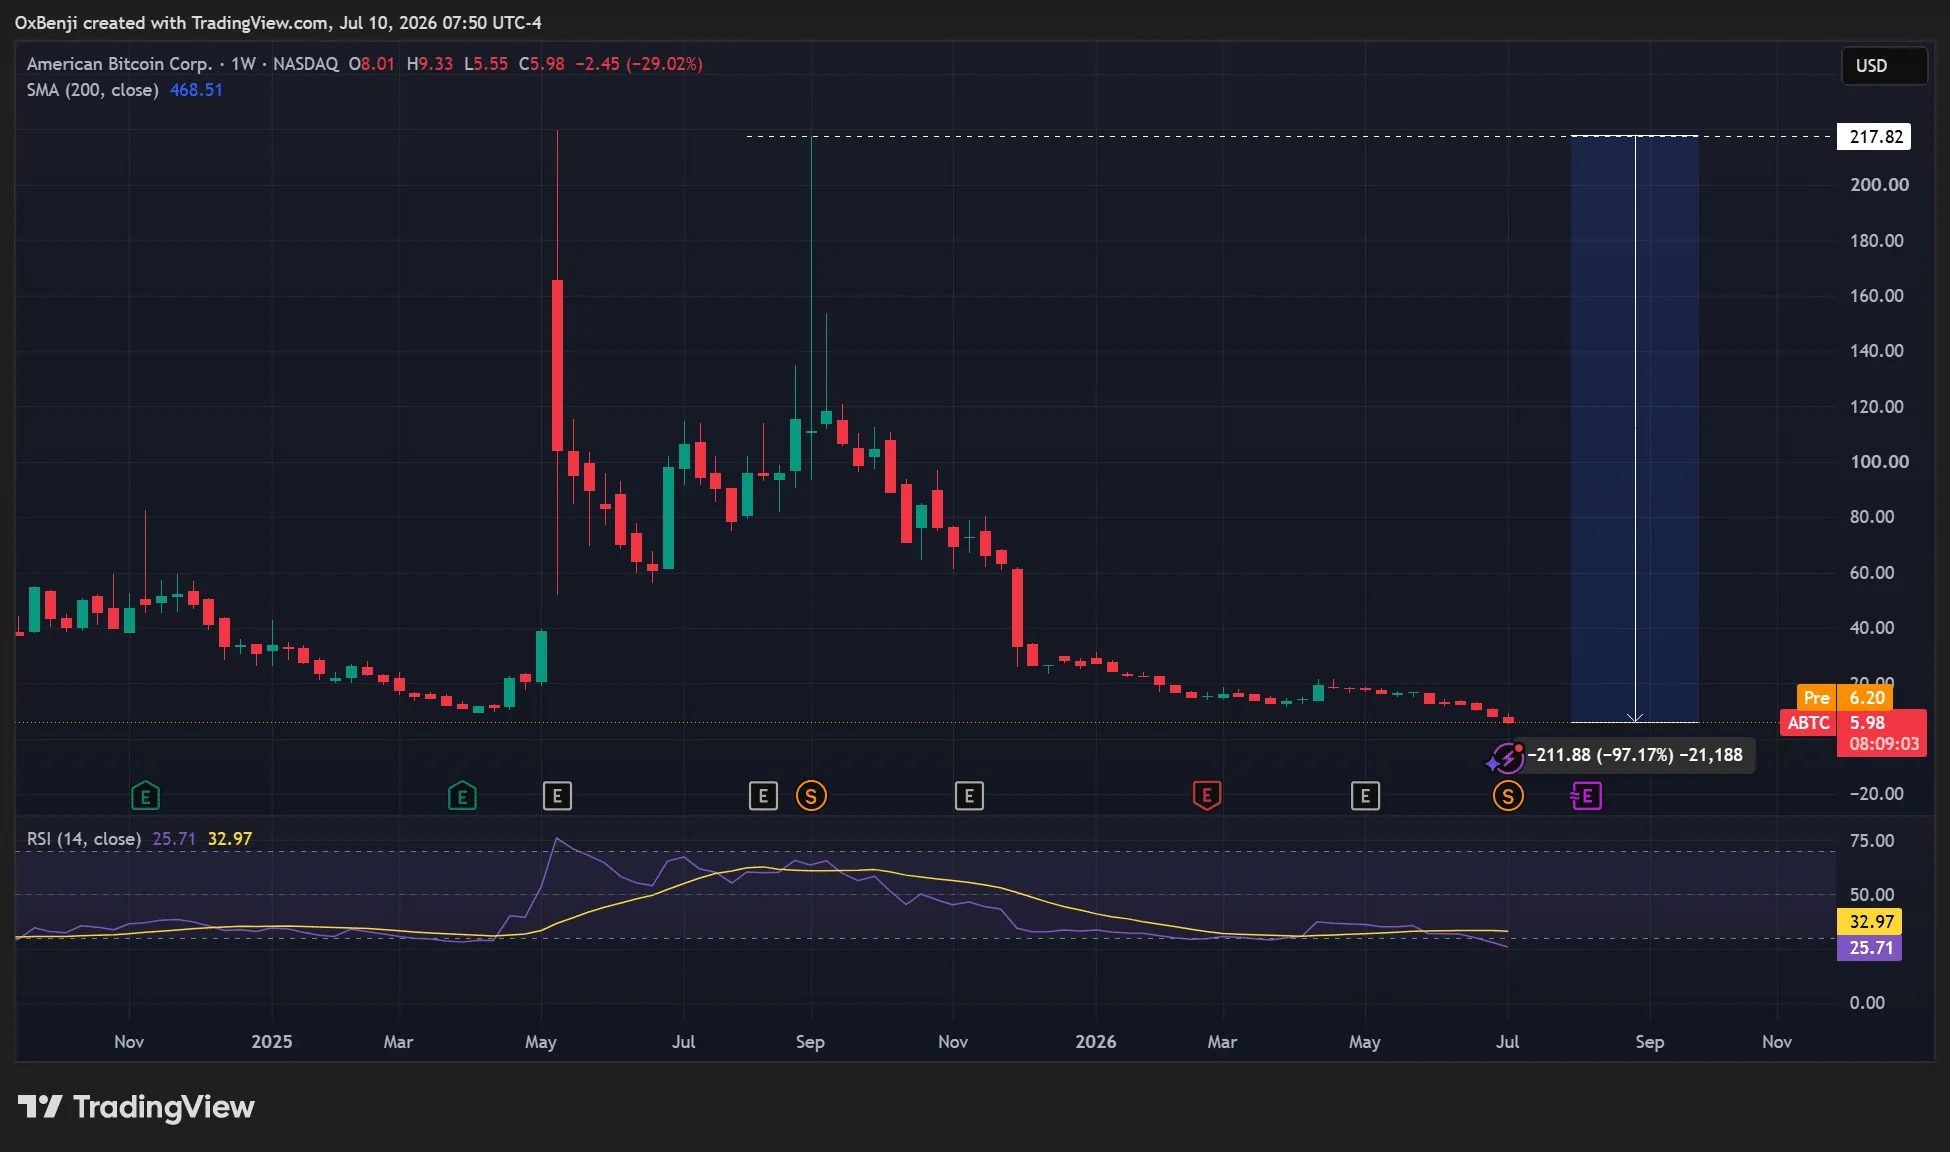
Amid the broader crypto downturn, the firm’s stock, ABTC, has plunged by 97%, crashing from September 2025’s peak of $217 to a record low of $5.98. This week alone, it dumped by over 29%.

Eric Trump American Bitcoin Corp
Source: ABTC, TradingView 

The massive stock dump forced the firm to launch a 1-for-5 reverse stock split on 2nd of July to remain listed on the Nasdaq. 

A company’s stock must maintain a minimum bid price of $1 to remain listed on the exchange. In fact, Nakamoto, another Bitcoin treasury firm, was forced to opt for a stock split to avoid a similar delisting. 

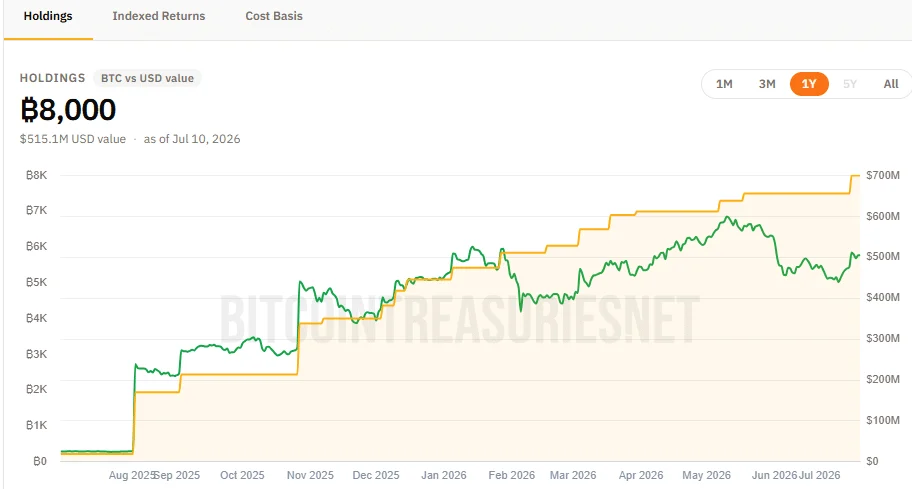
American Bitcoin Corp. scales holdings to 8,000 BTC

Despite the ongoing stock dump, however, the firm increased its BTC stash to 8,000 coins from 7,500 coins. 

Commenting on the same, Eric Trump downplayed the stock sell-off as just ‘crypto market volatility.’ In fact, he simply reiterated the commitment to ‘stacking’ more BTC at a discount. 

Even with crypto market volatility, I want to reiterate how we continue to differentiate ourselves, mining at a 52% profit margin in Q1 and continually adding to our treasury, all while maintaining one of the lowest SG&A ratios in the industry. The stacking continues.

Eric Trump American Bitcoin CorpEric Trump American Bitcoin Corp
Source: Bitcoin Treasuries 

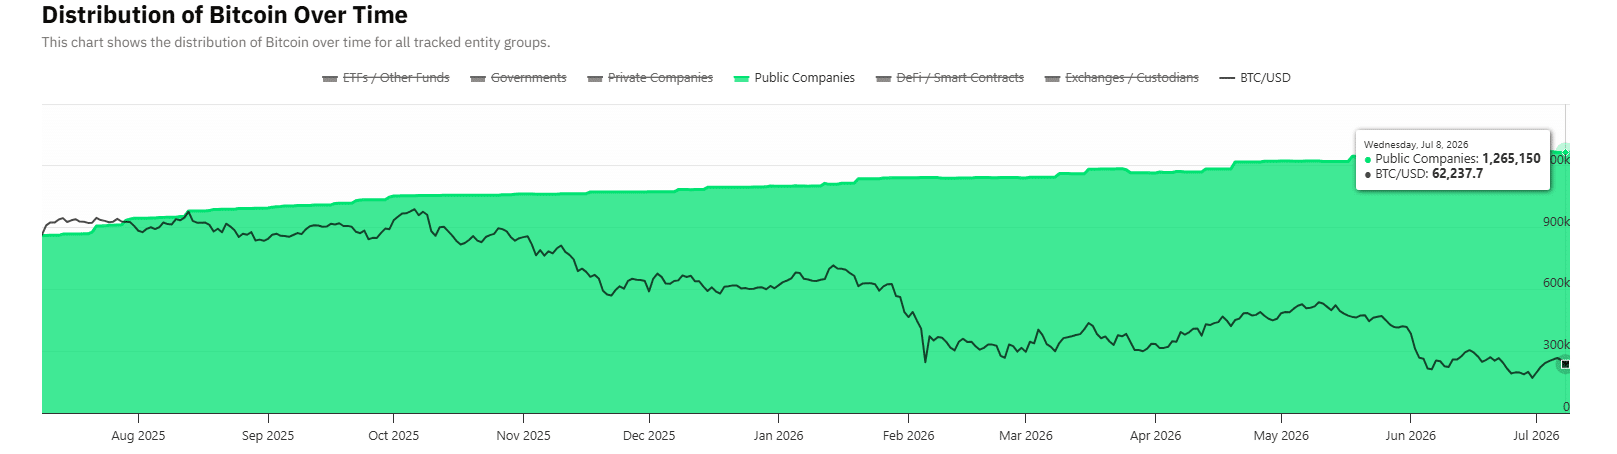
Separately, the broader Bitcoin treasury demand for the crypto asset has eased significantly after its largest buyer, Strategy, became a seller. Strategy recently sold $216M worth of BTC. 

In the last 30 days of trading, the demand from corporate treasuries has been negligible at 0.3%. In fact, after Strategy’s sale, the overall stash held by public companies dropped from 1.267M to 1.265M BTC. 

American Bitcoin Corp Eric trumpAmerican Bitcoin Corp Eric trump
Source: Bitcoin Treasuries 

The market faded the recent Strategy’s sale. However, whether it will help form a ‘durable market bottom’ for BTC and shore broader treasury demand remains to be seen. 


Final Summary

  • American Bitcoin Corp. stock dropped to a record low of $5.9 despite a recent reverse stock split. 
  • It has dropped by 97% from its last year peak of $217, erasing over $600M of Eric Trump’s stake in the firm.


Source link

Bitcoin’s $60,000-$70,000 range becomes third most traded range in history

0
Bitcoin's $60,000-$70,000 range becomes third most traded range in history


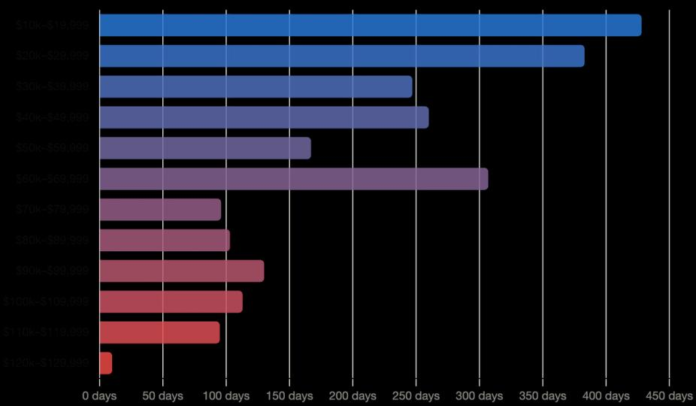
Bitcoin is trading around $64,000, marking 307 days within the $60,000- $70,000 range.

The consolidation range is now the third longest period spent in any $10,000 price band in bitcoin’s history, behind only the $10,000-$20,000 and $20,000-$30,000, according to Glassnode data.

From a technical perspective, bitcoin continues to trade above its 200-week moving average, currently around $62,873. Historically, prolonged moves below this level have been short lived, making it a closely watched gauge of the long term trend.

Despite holding near $64,000, bitcoin remains roughly 50% below its all-time high reached in October.

Onchain data also points to a significant area of support. Glassnode’s Entity Adjusted UTXO Realized Price Distribution, which tracks the price at which bitcoin last changed hands between economic entities, shows that about 6% of the circulating supply sits between $58,000 and $64,000.

Whether this range ultimately resolves higher or lower remains uncertain, but the prolonged sideways trading has established one of bitcoin’s largest cost-basis clusters to date.

UPDATE (July 10, 11:20 UTC): Amends hed from “Bitcoin’s $60,000-$70,000 range becomes third longest consolidation in history”


Source link